Skip to content

Onchain Private Credit Infrastructure for Lenders and Credit Funds

Protofire builds contracts for lenders and credit funds that tokenize notes or fund units. The contracts check servicer tapes against your eligibility rules, store the signed borrowing base and post NAV with its valuation date. You and your agents hold the keys. We built the LandX Credit Gateway on Arenas.
Luis Medeiros

Reviewed by Luis Medeiros, Field CTO at ProtofireLast reviewed: November 2026

On this page
  1. Overview
  2. Why it matters
  3. What you get
  4. Why Protofire
  5. How it runs
  6. Terms
  7. Platforms
  8. Not the right fit
  9. Related pages and blueprints
  10. FAQ

Work shipped for 60+ networks and 95+ protocols, including

  • Chainlink
  • Ethereum
  • Solana
  • Safe
  • Ripple
  • Aave

Moving borrowing base checks into contracts

A borrowing base checked in a spreadsheet against a weekly certificate can be a week old. Eligibility changes faster than that, so a borrower can draw against a base that is already too high. Onchain private credit infrastructure puts that check into contracts.

For example, the servicer's tape for the month-end determination date arrives on Monday. The borrower wants to draw on Tuesday, but your agent still works from last Wednesday's certificate. Over the weekend one obligor's invoices passed 90 days on 30-day terms, so the draw is now too big. Nobody sees that until someone opens the spreadsheet.

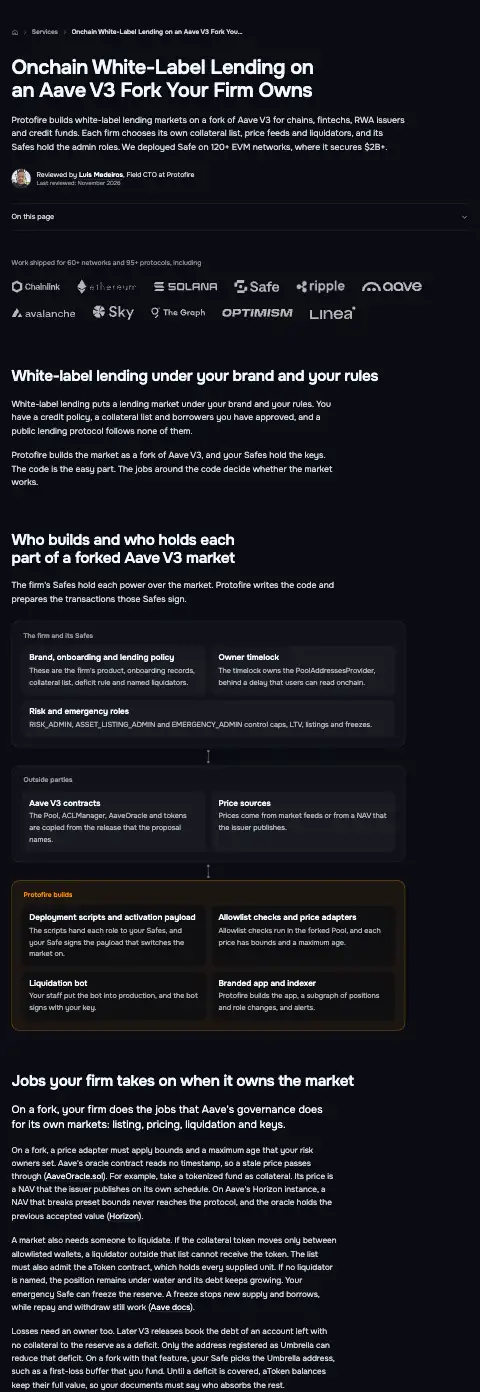
Parties and layers of a tokenized loan book

The lender and its agents produce and sign each figure. The layers Protofire builds check and post those figures.

The lender and its agents

Originator and credit policy

The originator underwrites, sets the servicing standard and offers loans to the facility.

Servicer and back-up servicer

The servicer runs collections and sends the loan tape on each determination date, and a back-up servicer stands by.

Appointed agents

Your documents appoint a trustee or security agent, a calculation agent, a paying agent and a fund administrator.
Protofire builds

Tape intake and eligibility checks

The contracts check each signed tape against the criteria in your credit agreement.

Borrowing base and draw limits

The contract stores each accepted base and rejects a draw above it.

Note or unit token

The token applies holder eligibility and transfer rules and records states such as Trigger breached or Event of default.

NAV and price posting

Each posted figure states its publisher, valuation date and maximum age.
Investors and venues

Investors and lending markets

Noteholders and fund investors hold the token, and lending markets list it.

Borrowing base and NAV figures go stale between updates

On invoices with 30 to 90 day terms, a weekly certificate can overstate what a borrower may draw.Because the base is the eligible balance times the advance rate, less reserves, each invoice that turns ineligible lowers it. In the OCC's example, an invoice past due by three times its terms is normally ineligible. Under cross-aging, all of an obligor's accounts become ineligible once the ineligible share reaches the level the agreement sets (OCC Comptroller's Handbook).

EU fund rules also depend on dated figures. Member States had to apply their laws transposing the AIFMD II loan rules from 16 April 2026. An EU fund whose strategy is mainly to originate loans is a loan-originating AIF. So is a fund whose originated loans reach "at least 50 %" of its net asset value. Such a fund has an exposure cap of 175% of NAV if open-ended and 300% if closed-ended. It must be closed-ended unless its manager shows the regulator that the fund's liquidity management fits its strategy and redemption policy (Article 16(2a)).

A stale figure costs more once the note or fund unit is a token, because a token can change hands between two tapes. Someone can then price a stale base, a NAV struck last month or a default the next strike will show, before the lender knows.

Limiting the outstanding balance of the ABL to a borrowing base provides the bank with greater assurance of full repayment from the value of the collateral. Borrowing base monitoring also provides an early warning system against credit deterioration.
Office of the Comptroller of the Currency (OCC), Comptroller's Handbook, US national bank regulator · Asset-Based Lending, Version 1.1, January 2017

What onchain private credit infrastructure gives a lender

Protofire builds each piece below from your own documents.

Draws capped at the accepted borrowing base

The contract rejects a draw that would lift loans outstanding above the lesser of the borrowing base and the commitment. It checks the servicer's signed tape loan by loan and logs each exclusion with the rule that caused it. It records the valuation date and signers of each accepted base. If a base falls below the outstanding balance, the contract sets an Over-advance state and your agreement's cure terms apply.

Each party signs its own step

The borrower certifies the base, and your agent accepts it or adds a reserve. The trustee or facility agent records a default, and the administrator publishes NAV. Each rule cites the clause it comes from, so your counsel can read the code against the document.

Transfer rules in the note or unit token

The token enforces the holder eligibility and transfer rules in your documents. Where the documents require it, the token stops transfers while Event of default is set. Protofire builds the note or unit token and the transfer rules and agent roles of a permissioned token.

NAV and price data for lending markets

Each figure posted onchain states its publisher, valuation date and maximum age. Chainlink posts the figure, or its publisher signs the update. Where a note claims backing, Protofire matches collateral figures to supply at one cut-off and flags stale inputs.

Lending market listings and block trades for the note

Protofire prepares the oracle and listing data that a lending market asks for, in Morpho markets and vaults or Aave's public markets and Horizon. Others run those markets, and the market's curator or governance decides the listing. Block trades between eligible holders can settle on dOTC contracts, a design we contributed to.

Payment date reports and back-up servicer handover

Protofire builds a report for each payment date from the posted figures and states. When a servicer is replaced, nothing is posted until the agent or trustee uses its role to register the back-up servicer's key. We write that handover down before launch.

Our record: LandX, Swarm Markets and proof of reserve

We built the LandX Credit Gateway on Arenas, Protofire's white-label lending product.White-label lending gives a firm a lending market it owns, for its own borrowers and lenders.

In 2021 Protofire built the DEX core (a Balancer fork) and the subgraph for Swarm Markets, and contributed to dOTC. Swarm Markets was a BaFin-licensed DEX at launch where only KYC-verified wallets trade. Swarm held the license and ran the KYC. For a credit token, the relevant part is trading restricted to verified wallets under a venue's own license.

For collateral figures, Protofire built and operated the reserve-data pipeline behind 15+ proof-of-reserve and real-time attestation deployments for asset-backed tokens, for a large auditing firm. The pipeline produced reserve data that an auditor reads.

How a private credit build with Protofire runs

Protofire starts from one sample tape.

  1. Step 1

    You send a sample tape

    You send a sample loan tape under NDA with borrower data removed, plus the eligibility criteria and advance rates from your documents. The servicer signs each tape with a key that your agent or trustee registered through its role before launch. The intake service stores each file's hash.
  2. Step 2

    We name each figure's signer

    Our proposal names the servicer, the agent that accepts the base and the NAV publisher it assumes. The intake service rejects a tape signed by any other key. If a base differs from the logged exclusions, it is held while the borrower and the agent see why.
  3. Step 3

    Build order, from intake to reports

    We build tape intake and eligibility first, then the base and draw limits, the token and NAV posting, and reports. Once a posting passes the chain's finality threshold, the reporting service records it under its valuation date. A post that timed out is checked on chain before it is retried.
  4. Step 4

    Your keys control the roles

    Your keys and your agents' keys control the roles in the facility from the first deployment, and no role answers to Protofire. Protofire may also operate a service that reads the contracts, under a written scope. Any write call that service makes uses keys or credentials that you or your agents keep.

How work with Protofire starts

Your procurement team can read the shared terms first.

Proposal
In writing, one business day after the discovery call: findings, a plan in phases and the first step we recommend.
Price
Fixed per phase when you commission it, against written acceptance criteria. Overruns inside them are ours to absorb, invoices follow delivered milestones, and you can stop at any phase boundary. Anything we operate after launch is priced in the proposal as its own recurring line, with the notice to end it.
Ownership
Code we write for you, contracts, the keys and credentials this work creates and the accounts your infrastructure runs in are yours by contract, within the license of any third-party software involved. Keys that a custody platform or a staking provider holds under its own key model stay with it under your contract; every other custody key stays with you or the custodian you appoint. Where the scope places something on servers we rent, it says what moves to you and when. An NDA is available from your first message, and we sign a data processing agreement (DPA) together with it.
After launch
Delivery closes with a hypercare window and a defect warranty, with their terms written into the proposal. A service we operate continues under its written scope until that scope ends.
Access
Read-only by default. A role that can start requests only if your written scope names one; never a signer, approver, administrator, key holder or recovery role on your contracts, wallets or custody platform. Services we build call each platform on credentials your staff issue and keep in your vault. Anything that approves or moves funds runs in your environment, and a scope under which we operate a service lists every write call it makes. Where the scope has us operate nodes, validators, monitors, explorers or indexers, it names the role and any key we hold on those servers, and in your own cloud account you can remove it.
Licenses
Protofire is an engineering firm and holds no financial or crypto-asset license; licensed activity stays with you and your providers.

How we work shows a worked proposal.

Platforms we integrate for private credit

A credit fund may issue on Centrifuge or Securitize, price through Chainlink and seek a listing on Morpho or Aave.Protofire connects each platform the fund chooses to the tape intake, the borrowing base and the NAV posting.

Centrifuge

Protocol for issuing and running tokenized funds.

Left to you: Investor KYC and the allowlist entries that follow it, NAV from your administrator, the register when a transfer agent keeps it, stablecoins on each network where investors redeem, and booking orders in your ledger.

Centrifuge integration

Securitize

Transfer agent, fund tokenization and investor onboarding APIs.

Left to you: Your onboarding screens and KYC, webhook and whitelisting status handling, balance reconciliation per chain, and eligibility state in any lending market you connect.

Securitize integration

Morpho

Isolated lending markets, variable and fixed rate, with curated vaults.

Left to you: Keys to any vault role you take and any allocator bot you run, checking each market's oracle, watching the curator's pending changes, your wallet structure, booking shares, in-kind exits and realized losses, the Powered by Morpho notice with its acknowledgment, and your own licensing.

Morpho integration

Aave

Lending protocol with a permissioned market for RWAs.

Left to you: Lenders and borrowers: the signing wallet, client attribution, interest and liquidation booking, and watching health factors and steward changes. Horizon borrowers: qualification with each fund's issuer, which keeps a role over the position.

Aave integration

Chainlink

Oracle feeds and CCIP for cross-chain transfers.

Left to you: Choosing feeds, the contracts that read them, and monitoring.

Chainlink integration

All 76 platforms we integrate

Where this build does not fit

  • One platform already issues and administers your fund units end to endSecuritize's ACRED page, read 11 November 2026, names Securitize entities as administrator, transfer agent and placement agent.
  • The token only needs a listing on an existing marketour guide to lending against tokenized collateral compares the venues.
  • You need a firm to hold a role in the facilityProtofire does not act as servicer or back-up servicer, as trustee or calculation agent, or as administrator or transfer agent. You appoint those parties directly. Protofire holds no license and gives no rating or legal opinion.
  • You want the code to bear the credit riska contract checks the arithmetic on the tape it is given. Field exams and audits check whether the tape is accurate. A contract does not underwrite. Your documents assign underwriting, the valuation of defaulted loans and any loss among the lender, servicer, administrator and holders.

The build fits a lender whose credit agreement or fund documents already name the servicer, the agent that accepts the base and the NAV publisher. That lender's token has to record the figures those three parties sign.

FAQ

What is onchain private credit infrastructure?
Onchain private credit infrastructure records a lender's loan-level figures on a blockchain, together with who signed each figure and when. The figures include eligibility results, the borrowing base, NAV and the note's states. Protofire builds it around the parties who sign those figures: the borrower and servicer, the facility agent or trustee, and the administrator.
Who can build the onchain side of a private credit fund or loan facility?
Protofire does. We build tape intake and eligibility checks, then the borrowing base contract, the note or unit token and the NAV posting. We connect them to the platforms you chose: Centrifuge or Securitize for issuance, Chainlink for prices, and Morpho or Aave for listing. Your documents decide who signs each figure.
How does a lending market price a credit token?
A lending market prices a credit token from a figure the fund's manager or administrator publishes, through an oracle the market's curator or governance chose. Chainlink's documentation says "NAV data is typically sourced from a single fund administrator or asset manager" (SmartData, read November 2026). On Morpho, a market's oracle is fixed at creation, and curators, "not Morpho", choose it (Morpho docs). A NAV struck monthly does not change while the loans age. So Protofire's contracts record the publisher, valuation date and age limit of each figure they accept, and stop new draws and subscriptions past that limit.
Does MiCA apply to a note token our vehicle issues?
MiCA does not apply if the token qualifies as a financial instrument, because MiCA excludes financial instruments (MiCA's Article 2(4)(a)). ESMA's guidelines cover a token for "a portion of a loan owed by the issuer". Where such a token is negotiable on the capital market, the guidelines say it should be considered a security with bond features. Your counsel classifies the instrument and the duties that follow.
When does a tokenized note become a securitization?
The EU definition of a securitization starts with credit risk that "is tranched" (Regulation 2017/2402, Article 2(1)). Payments then depend on the pool's performance, and subordination decides how losses fall. A junior token, or a subordinated loan that the originator keeps, can bring a tokenized issue within that definition. The originator, sponsor or original lender must then keep "a material net economic interest in the securitisation of not less than 5 %" (Article 6(1)). The Commission proposed amendments in June 2025 (procedure 2025/0826(COD)). Until an amending act is published in the Official Journal, the 2017 Regulation applies as adopted and amended. Your counsel decides whether a given note meets the definition.
Does our DORA register need an entry for this build?
Yes, for an authorized AIFM, which DORA covers along with the other financial entities it lists (Article 2(1)). Your register lists Protofire's build under ICT development, type S02. A service we operate that reads the contracts adds type S14. Both types are in Annex III of the implementing rules on the register. DORA does not apply to managers registered under Article 3(2) of the AIFMD. Your risk function and counsel choose what to file, and our DORA guide covers each service type.
Who can set an Event of default on the token?
The transaction documents give that power to one address. On a note, that is usually the trustee or security agent. On a loan, it is usually the facility agent acting for the required lenders. That party holds its key from deployment. The contract Protofire builds records who set the state and when, then stops transfers or draws as the documents provide.

Discussed on The Protocol Roundtable

All episodes

Get a proposal

Tell us what you are building. An engineer reads it, we have a short call, and the written proposal follows within one business day.

Luis MedeirosField CTO, reads every request · LinkedIn

A demo or repository link also works.