Fiat-Backed vs Crypto-Backed vs Algorithmic vs Synthetic: Choosing a Stablecoin Model
A builder's comparison of fiat-backed, crypto-backed, algorithmic, and synthetic dollars in 2026, from a team that ships stablecoin and yield-bearing-dollar infrastructure.
Reviewed by Luis Medeiros, Field CTO at Protofire · Updated October 2026
Fiat-backed stablecoins (USDC, USDT) hold cash and short Treasuries 1:1, dominate the ~$306B market, and fit new regulation, but concentrate trust in one issuer and pay holders nothing. Crypto-backed CDP dollars (USDS, ex-DAI) are over-collateralized and fully on-chain, at the cost of capital efficiency. Pure algorithmic stablecoins are effectively dead after Terra. Synthetic, delta-neutral dollars (Ethena's USDe) are a distinct fourth model that earns yield by hedging, and must not be confused with algorithmic. The right model depends on your regulatory footing, capital efficiency, and whether holders should earn yield.
Protofire builds stablecoin infrastructure, native issuance, yield-bearing dollars, and cross-border rails, so we have a commercial interest in the category. The comparison is model-agnostic, and the supply and peg figures come mostly from DefiLlama. See our other decision guides, including RWA token standards and cross-chain messaging.
At a glance
The four models
Fiat-backed
- +Simple, deeply liquid, and the regulatory default (GENIUS Act and MiCA are built for it)
- +Capital-efficient: every token is a dollar of reserves, held 1:1
- +Dominant by far: USDT and USDC are ~84% of all stablecoin supply
- −Trust concentrates in one issuer and the banking system (USDC depegged to $0.87 during the SVB failure)
- −Holders capture no yield; once the GENIUS Act is in force, payment stablecoins cannot pay interest to holders
- −Reserves are shown via monthly attestations, not full audits (Tether has never completed one), and issuer jurisdiction is an ongoing risk
A fiat-backed stablecoin holds cash and short-dated US Treasuries roughly 1:1 and holds its peg through issuer redemption and arbitrage. It is the simplest and most liquid model, and the one regulation is written for: USDC (~$73B) and USDT (~$183B) together are about 84% of the ~$306B market on 18 October 2026, a share that is slowly declining, perDefiLlama.
The trade-offs are trust and yield. Reserves sit with a centralized issuer and its banks, which is why USDC briefly depegged to $0.87 during the 2023 SVB failure, and the GENIUS Act (signed July 2025) both codifies the reserve rules and, once it takes effect, prohibits payment stablecoins from paying interest to holders, which is already why yield routes through separate products. In the EU, MiCA has treated these as e-money tokens since 30 June 2024; after ESMA told crypto-asset service providers in January 2025 to stop offering e-money tokens without an EU-authorized issuer (sell-only until the end of March 2025), EEA venues removed USDT trading between December 2024 and March 2025, while USDC stayed.
Crypto-backed (CDP)
- +Fully on-chain and verifiable collateral in real time, the transparency advantage
- +Censorship-resistant and DeFi-native, no bank dependency for the core mechanism
- +Recovered its peg across multiple cycles, though DAI briefly fell to ~$0.90 in the 2023 SVB event via its USDC exposure
- −Capital-inefficient: you lock $1.10 to $1.75+ of collateral per $1 minted
- −Exposed to liquidation cascades when collateral falls sharply
- −Decentralization is eroding as peg-stability modules lean on USDC and RWAs
A crypto-backed, collateralized-debt-position (CDP) stablecoin lets users lock volatile crypto in a vault and mint a dollar against it, with over-collateralization, automated liquidations, and a peg-stability module holding the peg. The canonical example rebranded in this cycle: MakerDAO became Sky in 2024 and launched USDS as DAI's upgrade; in April 2026 major exchanges force-converted DAI balances to USDS, though DAI itself remains live and immutable. Others include Liquity (LUSD and V2 BOLD), Curve's crvUSD (whose LLAMMA soft-liquidation is designed to avoid hard-liquidation cascades), and Aave's GHO.
Its advantage is transparency: the collateral is on-chain and verifiable in real time, and the mechanism does not depend on a bank. The costs are capital efficiency (you post well over a dollar of collateral per dollar minted) and liquidation risk if collateral drops fast. A subtle 2026 caveat: to defend the peg, these systems increasingly hold USDC and real-world assets in their stability modules, which dilutes the pure-decentralization claim.
Algorithmic
- +In theory, capital-efficient with little or no collateral to post
- +Decentralized by design, with no reserve or custodian
- +Included as a cautionary category; there is no healthy example at scale
- −Empirically fragile: reflexive depeg and death spirals with no collateral floor
- −Terra's UST (~$18B) collapsed in 2022; the combined UST and LUNA wipeout exceeded $40B
- −No pure algorithmic dollar has survived at scale since
A pure algorithmic stablecoin holds its peg by expanding and contracting supply against a paired token, with little or no hard collateral. In theory that is capital-efficient and decentralized; in practice it is reflexive and prone to death spirals, because there is no exogenous collateral floor to catch a loss of confidence.
The model is effectively dead at scale. Terra's UST collapsed in May 2022, and the combined UST and LUNA wipeout exceeded $40B, the defining seigniorage failure. Survivors reframed around real collateral (Frax, for one, moved from a fractional-algorithmic model toward full backing). We include it because a guide should say plainly why not to build a pure algorithmic dollar, not because it is a live option.
Synthetic (delta-neutral)
- +Native yield: the hedged position earns funding, paid through a separate staked token (sUSDe)
- +Capital-efficient (~1:1), with a real hedged portfolio behind it
- +Largest synthetic dollar, Ethena's USDe, is a real, sizable product
- −Funding-rate risk: negative perp funding erodes the backing
- −Exchange and custody counterparty risk (reserves sit on CEXs and with custodians)
- −A demonstrated flash-depeg history (USDe printed ~$0.65 on one venue in October 2025)
A synthetic, delta-neutral dollar is backed by a hedged position, long spot crypto and an equal short perpetual future, so price exposure nets to about zero and the peg rests on the hedged portfolio plus mint-and-redeem arbitrage. This is not seigniorage, so calling it algorithmic (as some trackers do) is wrong. Ethena's USDe (~$4.7B, down from a ~$15B peak in October 2025) is the largest example, and its staked form, sUSDe, pays a variable yield, often in the teens or higher in 2024 but mostly 4 to 9% in 2025 and roughly 4% by mid-2026 as perpetual funding cooled.
The risks are specific. Funding rates can turn negative and erode the backing, so Ethena runs a reserve fund to absorb that and rotates part of the backing into stablecoins and tokenized Treasuries when funding is thin (meaning the backing is not purely spot-plus-perp). The collateral also lives on exchanges and with custodians rather than in a public vault, a real counterparty risk, the same bucket that sank Elixir's deUSD in November 2025 when its backing was parked with a failing external manager and fell to about $0.02. USDe itself printed as low as ~$0.65 on one venue during the October 2025 selloff, an order-book dislocation rather than a reserve failure, and held near par elsewhere. One legal nuance: once the GENIUS Act's ban on payment-stablecoin interest is in force, designs like this must separate yield into a staked token, which is already why USDe itself is not yield-bearing but sUSDe is.
Which should you use?
you want the model regulation is written for (GENIUS, MiCA), maximum liquidity, and simple 1:1 backing, and holders earning yield is not the point.
you want a fully on-chain, verifiable dollar and can accept capital inefficiency and liquidation risk.
you want a capital-efficient dollar that earns yield through hedging, and you understand the funding-rate and exchange-counterparty risks; never market it as cash-like.
there is no healthy example at scale; if capital efficiency is the goal, use over-collateralization or a hedged model, not seigniorage.
Adjacent instruments and context
- Machine payments: x402 payments by AI agents settle almost entirely in USDC; the agentic payment protocols guide compares x402, MPP, AP2, ACP and the card-network programs.
- Euro tokens: for a fiat-backed euro token, euro stablecoins compared sets EURC, EURCV, EURI, EURe, EURØP, EURQ and EURAU side by side on issuer, license, supply and redemption.
- Bank-issued money: a regulated bank can also put deposits on chain as a deposit token instead of issuing a stablecoin; the tokenized deposits vs stablecoins guide sets the two side by side.
- In production: the euro EMT issuance blueprint shows an institution issuing its own MiCA e-money token, with the reserve and transparency operation and named issuers.
- Tokenized money-market funds (BlackRock BUIDL, Circle USYC): not stablecoins. They are tokenized fund shares that DO pay yield, either at a $1 price with dividends paid as new tokens (BUIDL) or through a rising token price (USYC), restricted to whitelisted holders. They are the institutional-cash complement to a payment stablecoin, not a substitute, and they exist partly because payment stablecoins legally cannot pay yield.
- RWA-backed / yield-bearing dollars (Ondo USDY, Ethena USDtb): tokens that look like a stablecoin but pass through Treasury yield, usually structured as securities to stay legal under the GENIUS no-yield rule.
- Regulatory currency: the US GENIUS Act (2025) sets reserve, disclosure, and no-yield rules for payment stablecoins, with rulemaking through 2026 and effect on 18 January 2027; MiCA's e-money-token rules applied from 30 June 2024, and by the end of March 2025, following ESMA's January 2025 statement, EEA venues had stopped trading USDT, which has no EU-authorized issuer, while USDC stayed. Confirm the framework with counsel before issuing.
- Paying out: moving a fiat-backed token to beneficiaries is a separate choice of provider; BVNK, zerohash, Bridge, Circle Payments Network and others are compared in stablecoin payout rails.
FAQ
Is USDT banned in Europe under MiCA?
What is the most common type of stablecoin?
Are algorithmic stablecoins dead?
Is Ethena's USDe an algorithmic stablecoin?
How do the GENIUS Act and MiCA affect which model to build?
Discussed on The Protocol Roundtable
All episodes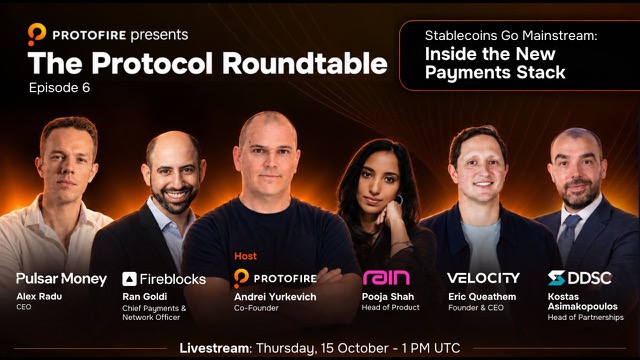
Which stablecoins shops in the UAE may accept
 Kostas Asimakopoulos, DDSC
Moment at 24:29Episode 6 · Stablecoins Go Mainstream: Inside the New Payments Stack
We build stablecoin systems: the collateral and peg mechanics, oracle and liquidation design, reserve attestation, and the governance and monitoring that keep them solvent.
native stablecoin development →Get a proposal
Tell us what you are building. An engineer reads it, we have a short call, and the written proposal follows within one business day.
Budget
An NDA is available from the first message and can cover anything you share. How it works