Prediction Market Leverage for Venues, Lending Protocols and Funds
Protofire builds lending against outcome tokens for prediction market venues, lending protocols and funds on EVM chains. We build the collateral and price adapters, the cut-off before resolution and the one-transaction loan, and your Safes hold the roles. In 2020 and 2021 we built the Conditional Tokens Explorer for Gnosis.
Reviewed by Luis Medeiros, Field CTO at ProtofireLast reviewed: November 2026
On this page
Work shipped for 60+ networks and 95+ protocols, including




An outcome token is collateral with an end date
An outcome token stops trading on the day its market resolves, and a loan against it needs rules for that day. Protofire builds the lending layer behind prediction market leverage for venues, lending protocols and funds on EVM chains.
For example, a trader borrows the venue's stablecoin against a YES position, and the market then resolves to NO. The YES token is worth nothing, and the loan has no collateral left.
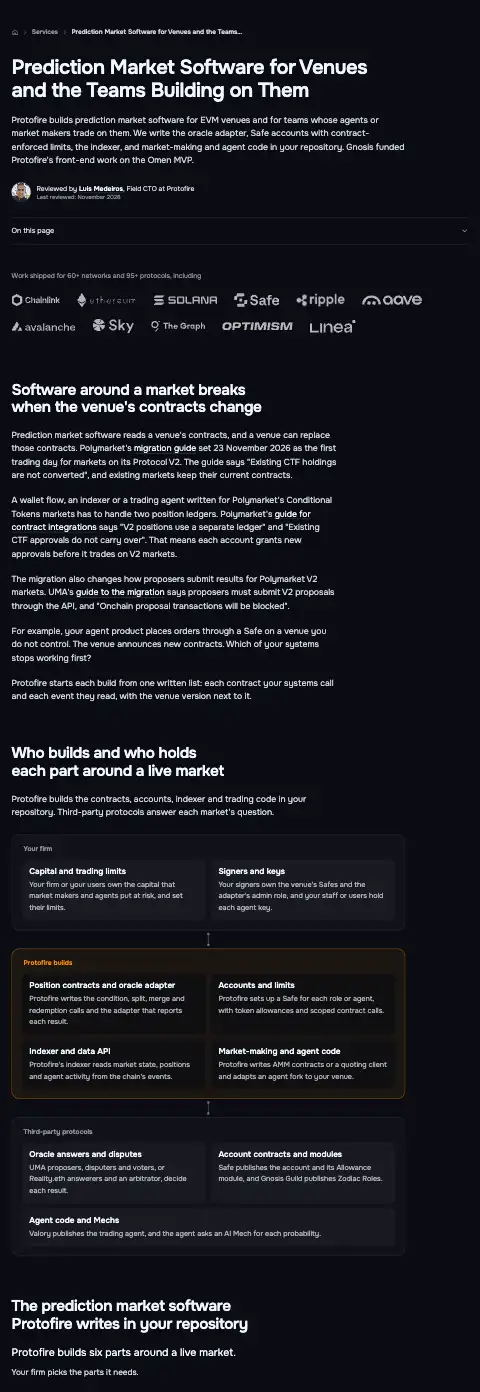
Who holds each part of a loan against an outcome token
Protofire builds the adapters, the checks and the loan contract.
Market rules
Position ledger
Listing file and loss rule
Admin roles
Oracle answer
Lending market
Adapters and checks
Loan contract, bot and indexer
What a lender holds when a market resolves
A lender's collateral stops trading when its market resolves, so the lender has no order book to sell it into.On Polymarket, winning tokens then redeem for $1.00 each, and losing tokens "become worthless". A 50/50 result redeems each token for $0.50.
On Polymarket's UMA-resolved markets, the oracle's answer comes after a challenge period. An undisputed result arrives about two hours after the proposal, and a disputed one takes four to six days in all. Protofire builds a venue's own market contracts and resolution path as a separate service.
When collateral resolves to $0, the debt behind it becomes a loss. Morpho's documentation states the problem: "There is no incentive for the liquidator or borrower to repay the remaining debt". On a Morpho Blue market, the suppliers share that debt once a liquidation seizes the last collateral. No liquidation bot removes the loss once a token has resolved to $0.
The collateral is also changing. Polymarket's migration guide says new markets begin trading on a second position ledger in phases, the first on 23 November 2026. The guide also says "Existing CTF holdings are not converted". So an adapter and a price source built for Conditional Tokens IDs do not cover the new position IDs.
Without a lending layer of its own, a venue leaves traders who want to borrow to contracts it does not control. A lender with a general-purpose setup holds collateral that can be worth nothing two hours after an oracle proposal.
Event Contracts are fully collateralized and are not traded on margin.
Three designs for lending against outcome tokens
The table compares three designs for loans against outcome tokens, and they differ on who sets the limit and who takes a loss.The third design comes from PolyLend, a repository in Polymarket's GitHub organization. Its README calls it "an experimental peer-to-peer lending protocol allowing users to borrow USDC against conditional token positions". The README also says the contract is "unaudited". Protofire builds on the first two designs.
Who sets the loan limit
Isolated Morpho Blue market: The market's creator, from a list that Morpho governance approved. The limit cannot change after creation (Morpho Blue)
Lending market you own on an Aave V3 fork: Your risk Safe, which can lower it or freeze the collateral before a result (white-label lending)
Two-party loans with no price oracle: The borrower and a lender. The borrower requests a loan, and the lender offers an amount and a rate
Where the price comes from
Isolated Morpho Blue market: One oracle with a single price() function, chosen at creation
Lending market you own on an Aave V3 fork: A price adapter with the bounds and maximum age that your risk owners set
Two-party loans with no price oracle: The contract reads no price
Who liquidates
Isolated Morpho Blue market: Outside liquidators, for the collateral plus a bonus
Lending market you own on an Aave V3 fork: Your firm decides who liquidates. In Aave V3's code, the liquidation call has no caller restriction
Two-party loans with no price oracle: No one. The lender can call the loan after its minimum duration, and a one-day auction offers it to new lenders
Who takes a loss
Isolated Morpho Blue market: The market's suppliers, or a vault's shareholders
Lending market you own on an Aave V3 fork: Whoever your deficit rule names
Two-party loans with no price oracle: The lender, who reclaims the collateral if no new lender takes the loan
What Protofire builds for prediction market leverage
Your risk owners set the limits in each part that Protofire builds.
A lending market that accepts outcome tokens
Your traders or borrowers post outcome tokens as collateral under limits your risk owners sign. Protofire prepares an isolated market on Morpho Blue or a lending market your firm owns on an Aave V3 fork.
An adapter for each position ledger
Your lending market accepts outcome positions as collateral. Your market contracts do not change. Protofire's adapter wraps each ERC-1155 position into an ERC-20 token and unwraps it for redemption.
A price source for each listed token
Your firm owns the price source for each outcome token, and the market reads one price within bounds and a maximum age. A Morpho Blue market fixes its limit at creation, so Protofire builds a discount that grows toward the end date into the adapter.
A cut-off before each market's end date
Your risk owners decide which markets are eligible and when new loans stop before each end date. Protofire builds the contract checks for the cut-off and for the owners' rules on an oracle proposal, a split payout or a "too early" answer.
A loan opened in one transaction
Your traders wrap a position, post it as collateral and borrow in one transaction from your buy panel. Protofire builds the loan contract, and the transaction reverts as a whole if one step fails.
A liquidation bot and an indexer
Your team reads each position and each loan's health from an indexer that Protofire builds. As an option, Protofire writes the liquidation bot, which signs with your key from hosts closed to Protofire.
Lending against a position raises a second legal question
A venue already answers whether a person may trade.A loan against a position adds two questions: may this person borrow, and may this firm lend?
In the US, the Commodity Exchange Act covers commodity transactions offered "on a leveraged or margined basis, or financed by the offeror" (7 U.S.C. 2(c)(2)(D)). The provision applies, with exceptions, when the customer is not an eligible contract participant or eligible commercial entity.
The CFTC has proposed to further define the term swap to explicitly include event contracts, including those on sports and politics. The Federal Register published the proposal on 19 October 2026, and it asks for comments by 18 November 2026 (read 16 November 2026).
Counsel decides whether a venue, a lender or a fund may offer loans against positions, and to whom. Protofire gives no legal opinion. Protofire builds the allowlist and location checks that counsel specifies.
Our record: Conditional Tokens, lending, oracles and Safe
Protofire's record for this service starts with Gnosis's Conditional Tokens framework.
Gnosis's Conditional Tokens Explorer and Omen front end
In 2020 and 2021 we built the Conditional Tokens Explorer for Gnosis, a web app that runs each operation of the framework from a screen. Gnosis's announcement of the Conditional Tokens Explorer, on 9 December 2020, points readers to Protofire's account of its contribution to developing it. Gnosis designed the framework and its contracts. Gnosis funded Protofire to do the front-end development of the Omen prediction-market MVP (Gnosis forum, 20 January 2021). The Explorer ran split, merge, report and redeem, and a collateral adapter and a liquidation path call the same framework.
The LandX Credit Gateway and Tezos Foundation grants
Protofire built the LandX Credit Gateway on Arenas. In 2019 the Tezos Foundation granted Protofire funds to build a Tezos liquidity-pool contract with a demo client and tutorials. Later, the Foundation granted Protofire funds to add lending and borrowing.
Chainlink core contribution and Somnia's oracle stack
Protofire is a Chainlink core contributor. In 2025 Protofire built Somnia's Chainlink-compatible oracle stack. Five oracle nodes in OCR consensus backed three mainnet price feeds and VRF. We operated the stack until the engagement ended in late 2025. A price adapter for an outcome token is oracle work.
Safe for the roles of a lending market
The Safe Ecosystem Foundation wrote in May 2026 that Protofire "has been contributing to Safe since 2018". We deployed Safe on 120+ EVM networks, where it secures $2B+.
From one market's rules to a loan your Safes control
- Step 1
Listing file and written proposal
Protofire proposes a listing file with the eligible markets, the limit for each and the cut-off before each end date. Your risk owners decide each value and sign it. Protofire's written proposal names the route, and for an Aave V3 fork the release that the fork copies. A wrong parameter on Morpho Blue means a new market. - Step 2
Solidity contracts and an outside audit
Protofire writes the adapters, the checks and the loan contract in Solidity. The code goes to an outside audit firm, and Protofire prepares the code for the audit and fixes the findings. An audit lists findings. It does not promise that the code is free of faults. - Step 3
Deployment from your keys, then handover
Your engineer deploys from your keys, and each admin role goes to your Safes. You own the contracts that Protofire writes, their code and the keys. If you want Protofire to run the indexer or position monitoring after launch, we do so under a written scope.
How work with Protofire starts
Work on loans against outcome tokens starts with the markets you plan to list and the position ledger behind each one.You also send the chain, the route you prefer and the Safe addresses that will hold each role.
- Proposal
- In writing, one business day after the discovery call: findings, a plan in phases and the first step we recommend.
- Price
- Fixed per phase when you commission it, against written acceptance criteria. Overruns inside them are ours to absorb, invoices follow delivered milestones, and you can stop at any phase boundary. Anything we operate after launch is priced in the proposal as its own recurring line, with the notice to end it.
- Ownership
- Code we write for you, contracts, the keys and credentials this work creates and the accounts your infrastructure runs in are yours by contract, within the license of any third-party software involved. Keys that a custody platform or a staking provider holds under its own key model stay with it under your contract; every other custody key stays with you or the custodian you appoint. Where the scope places something on servers we rent, it says what moves to you and when. An NDA is available from your first message, and we sign a data processing agreement (DPA) together with it.
- After launch
- Delivery closes with a hypercare window and a defect warranty, with their terms written into the proposal. A service we operate continues under its written scope until that scope ends.
- Access
- Read-only by default. A role that can start requests only if your written scope names one; never a signer, approver, administrator, key holder or recovery role on your contracts, wallets or custody platform. Services we build call each platform on credentials your staff issue and keep in your vault. Anything that approves or moves funds runs in your environment, and a scope under which we operate a service lists every write call it makes. Where the scope has us operate nodes, validators, monitors, explorers or indexers, it names the role and any key we hold on those servers, and in your own cloud account you can remove it.
- Licenses
- Protofire is an engineering firm and holds no financial or crypto-asset license; licensed activity stays with you and your providers.
How we work shows a worked proposal.
Where a lending layer does not fit
A lending layer from Protofire fits a venue, a lender or a fund whose positions are tokens on an EVM chain.
- Your venue's positions are exchange accounts, as on Kalshi, which a lending contract cannot hold. Margin on them is a matter for the venue and its regulator.
- You want perpetual futures on asset prices. Our perp DEX development service builds a perpetuals exchange.
- You want Protofire to supply the loan asset or act as the liquidator of record. Protofire lends nothing and holds no keys, no license and no oracle role.
- Your markets run on Solana or another non-EVM chain. Protofire's contract work is Solidity on EVM chains.
Related guides and services
FAQ
What is prediction market leverage?
Can traders borrow against Polymarket or Kalshi positions today?
What happens to a loan against an outcome token when the market resolves?
Who can build lending against outcome tokens for a venue, a lending protocol or a fund?
Get a proposal
Tell us what you are building. An engineer reads it, we have a short call, and the written proposal follows within one business day.